SemiAnalysis
Jul 29, 2026
bullish
Neoclouds Demanding 100% Prepays as Chip Production Becomes Binding Constraint
SemiAnalysis reports that only a handful of neoclouds are still offering 1-year GPU rental contracts, and those that do are requiring prepayment of up to 100% of total contract value upfront. The firm notes that by early 2026 the datacenter supply situation had improved considerably, but chip production has now emerged as the new limiting constraint on capacity growth. Providers are effectively funding cluster capex entirely from customer prepays, reflecting the degree of pricing power now held by the supply side.
GetDeploying GPU Price Index
Jul 31, 2026
neutral
Broad Cloud GPU Rental Index Edges Down 0.7% Over Four Weeks
GetDeploying's weekly index across 69 providers and 27 GPU models showed aggregate on-demand GPU rental prices down 0.7% over the four weeks ending July 31, while remaining up 4.7% year-over-year. The biggest single-week movers (week of July 27) were concentrated in mid- and low-tier models, with the GB200 down 15% on the week. High-performance datacenter SKUs such as H100 and B200 showed no comparable softening in the index.
SemiVision Weekly Intelligence
Jul 31, 2026
neutral
AI Infrastructure Competition Shifts from GPU Access to Full Supply-Chain Integration
SemiVision's July Week 4 dispatch, citing signals from Samsung, SK Hynix, Lam Research, Microsoft, and Meta, argues that the center of AI compute competition is migrating from GPU procurement toward control of the entire infrastructure stack — HBM memory, CoWoS packaging, power, and optical interconnects. The implication for rental pricing is that raw GPU availability is no longer the sole bottleneck; operators unable to integrate these ancillary inputs may face capacity ceilings even with chip allocations secured.
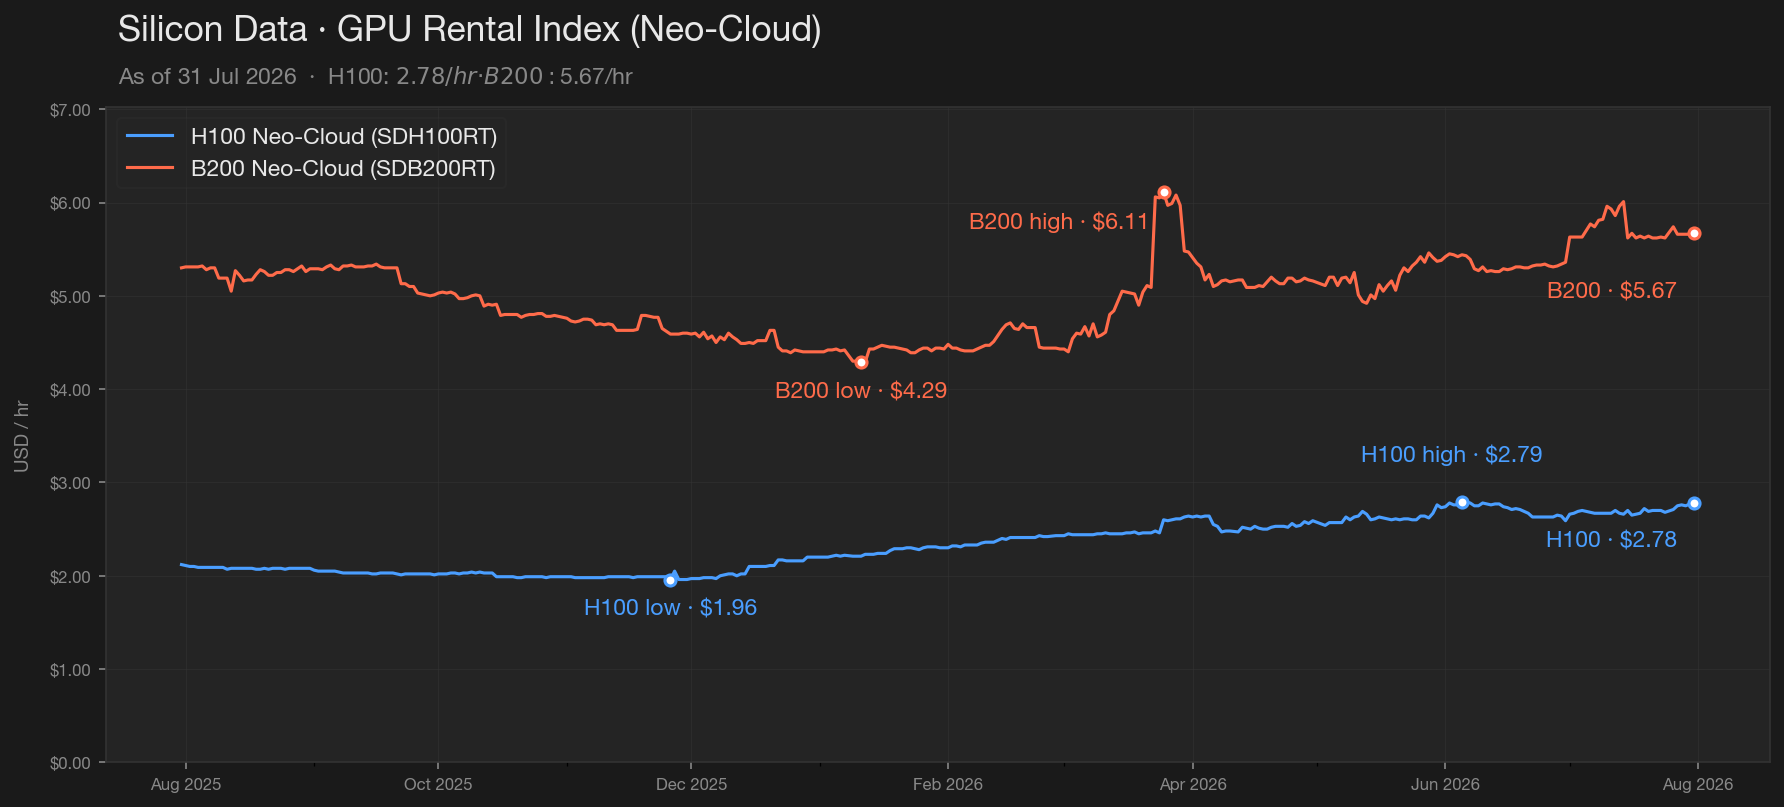
The SDH100RT (H100 Neo-Cloud) closed July at $2.78/hr, up 3.0% over 10 days and 4.5% over 30 days — the strongest momentum reading on the index. This is consistent with the broader supply-tightness picture: SemiAnalysis reports that neoclouds are now demanding up to 100% prepayment on 1-year contracts, with chip production — not datacenter capacity — the binding constraint on new supply. The SDB200RT (B200 Neo-Cloud) at $5.67/hr remains comparatively flat (+0.9% / +0.7%), suggesting Blackwell capacity is being absorbed steadily but without the acute spot-market squeeze visible in Hopper. The broad-market GetDeploying index, updated July 31, shows aggregate GPU rental prices edged down 0.7% over the last four weeks, meaning H100 neo-cloud rates are meaningfully outperforming the composite — a signal of selective tightness at the high-performance end rather than a market-wide bid.